AS-ISHOUSE BUYERSof Chicagoland
How it worksSell as-isSituationsAreas we serveAboutFAQ
224-219-0970

Pre-foreclosure

Behind on the mortgage in Illinois, with no case filed yet.

You still own the house, and no court case has started. This is the stage with the most options, and selling is only one of them. We're a buyer, not your advisor: talk to a housing counselor first, then ask us for an offer if a sale makes sense.

Todd Bennett, owner of As-Is House Buyers of Chicagoland

Todd Bennett, OwnerBuying houses since 2008

Start your offer

✓Start with the address. You are not agreeing to sell by sending it.

“We had an excellent experience selling our home in McHenry County, IL.…”

Alison M. · January 2026 GoogleFrom our owner’s earlier home-buying business. Excerpt from a Google review.

By Todd Bennett, owner · Updated October 3, 2026

Missing mortgage payments isn't the same as being in foreclosure. In Illinois a foreclosure is a court case, and until one is filed there's no judgment, no sale date, and no statutory clock running. This page covers that earlier stage. If you've already been served with a summons, our foreclosure page covers that stage instead.

We can look at the house and put an offer in writing, with no obligation. We don't negotiate with your lender, and we can't tell you how any choice will affect your credit.

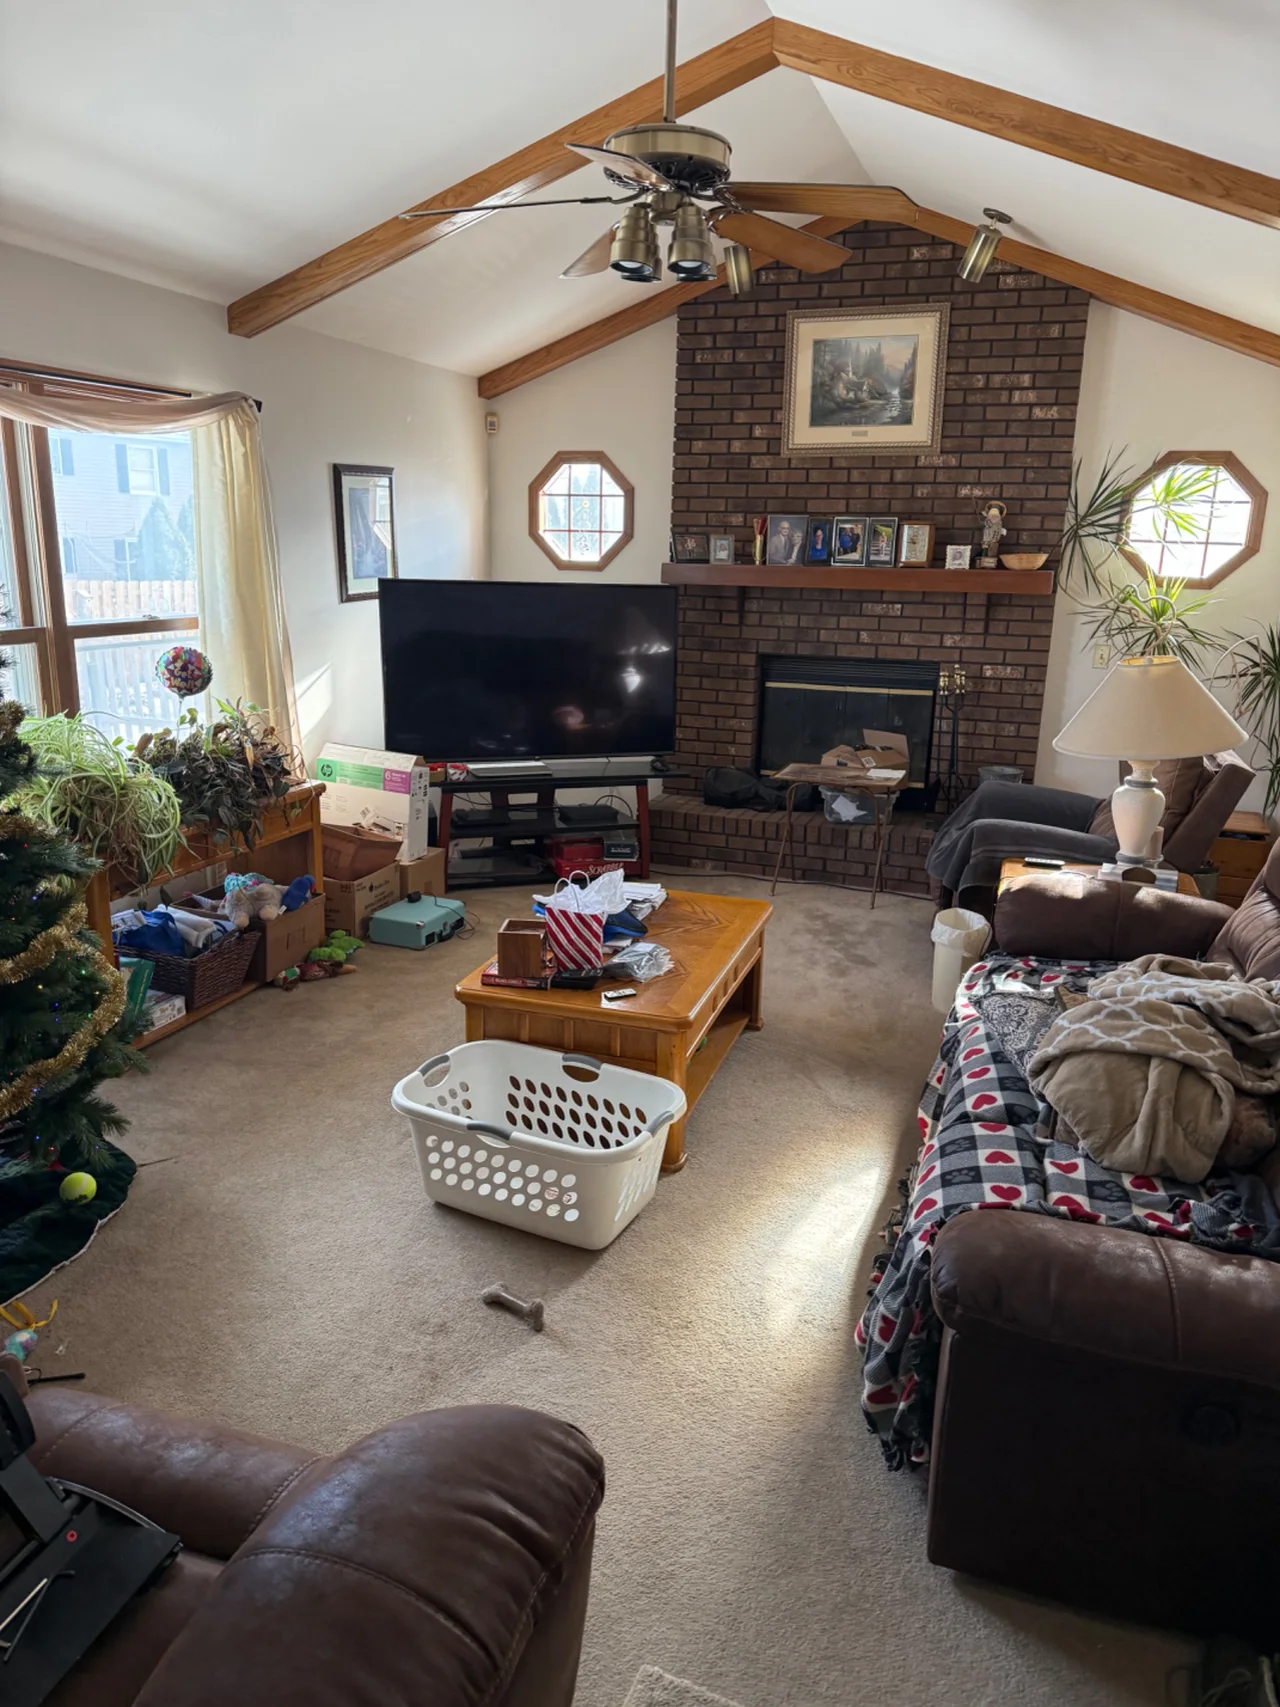
Furnished family room with a brick fireplace and exposed ceiling beams

Good to know: Legal and financial details vary by situation. This page offers general information, not legal or tax advice. Talk with a qualified Illinois professional about your circumstances before signing an agreement.

01

What we do

What has to happen before a lender can foreclose

Two rules set the floor. Federal mortgage servicing rules generally say a servicer can't make the first notice or filing for a foreclosure until the loan is more than 120 days delinquent, with exceptions such as a due-on-sale violation. And Illinois doesn't let a lender sell a house under a power of sale in the mortgage: the lender has to file a lawsuit and win a judgment first.

If a case is filed, you'll be served with a summons, and Illinois requires a Homeowner Notice attached to it that lists your rights in plain language; our page on selling a house in foreclosure in Illinois goes through it. Until then, the letters from your servicer are notices, not court papers. Read them, keep them, and don't assume either that you have months or that you don't. How those rules apply to your loan is a question for your servicer and a housing counselor.
02

Call a housing counselor before you call a buyer

HUD-approved housing counseling agencies give independent advice, often at little or no cost, and the Consumer Financial Protection Bureau keeps a search tool for finding one near you. A counselor can go through what your servicer offers: a repayment plan, a modification, forbearance, or other workout. Those are between you and your lender. We have no part in them and can't get them for you.

If you want to keep the house and there's a realistic way to catch up, that's a better outcome for you than selling to us. We'd rather you find that out from a counselor before we ever walk through.

03

When selling is the better choice

Selling makes sense when the payment no longer fits and isn't going to, when the house needs work you can't fund, or when you'd rather leave with your equity than spend it catching up. Before a case is filed, a sale is an ordinary sale: the mortgage is paid from the price at closing, along with any other liens, and what's left is yours.

Start with the payoff. Ask your servicer for a written payoff statement, and ask a title company to check for a second mortgage, an association balance, unpaid taxes, or judgments. If the search turns up an IRS lien, a state tax lien, or a judgment, our guide on selling a house with a tax lien or judgment explains how each is paid at closing. If the total is more than the house will sell for, a sale needs the lender's approval as a short sale, and that's a conversation to start with a counselor or a lawyer.

04

Who finds out, and how a sale to us works

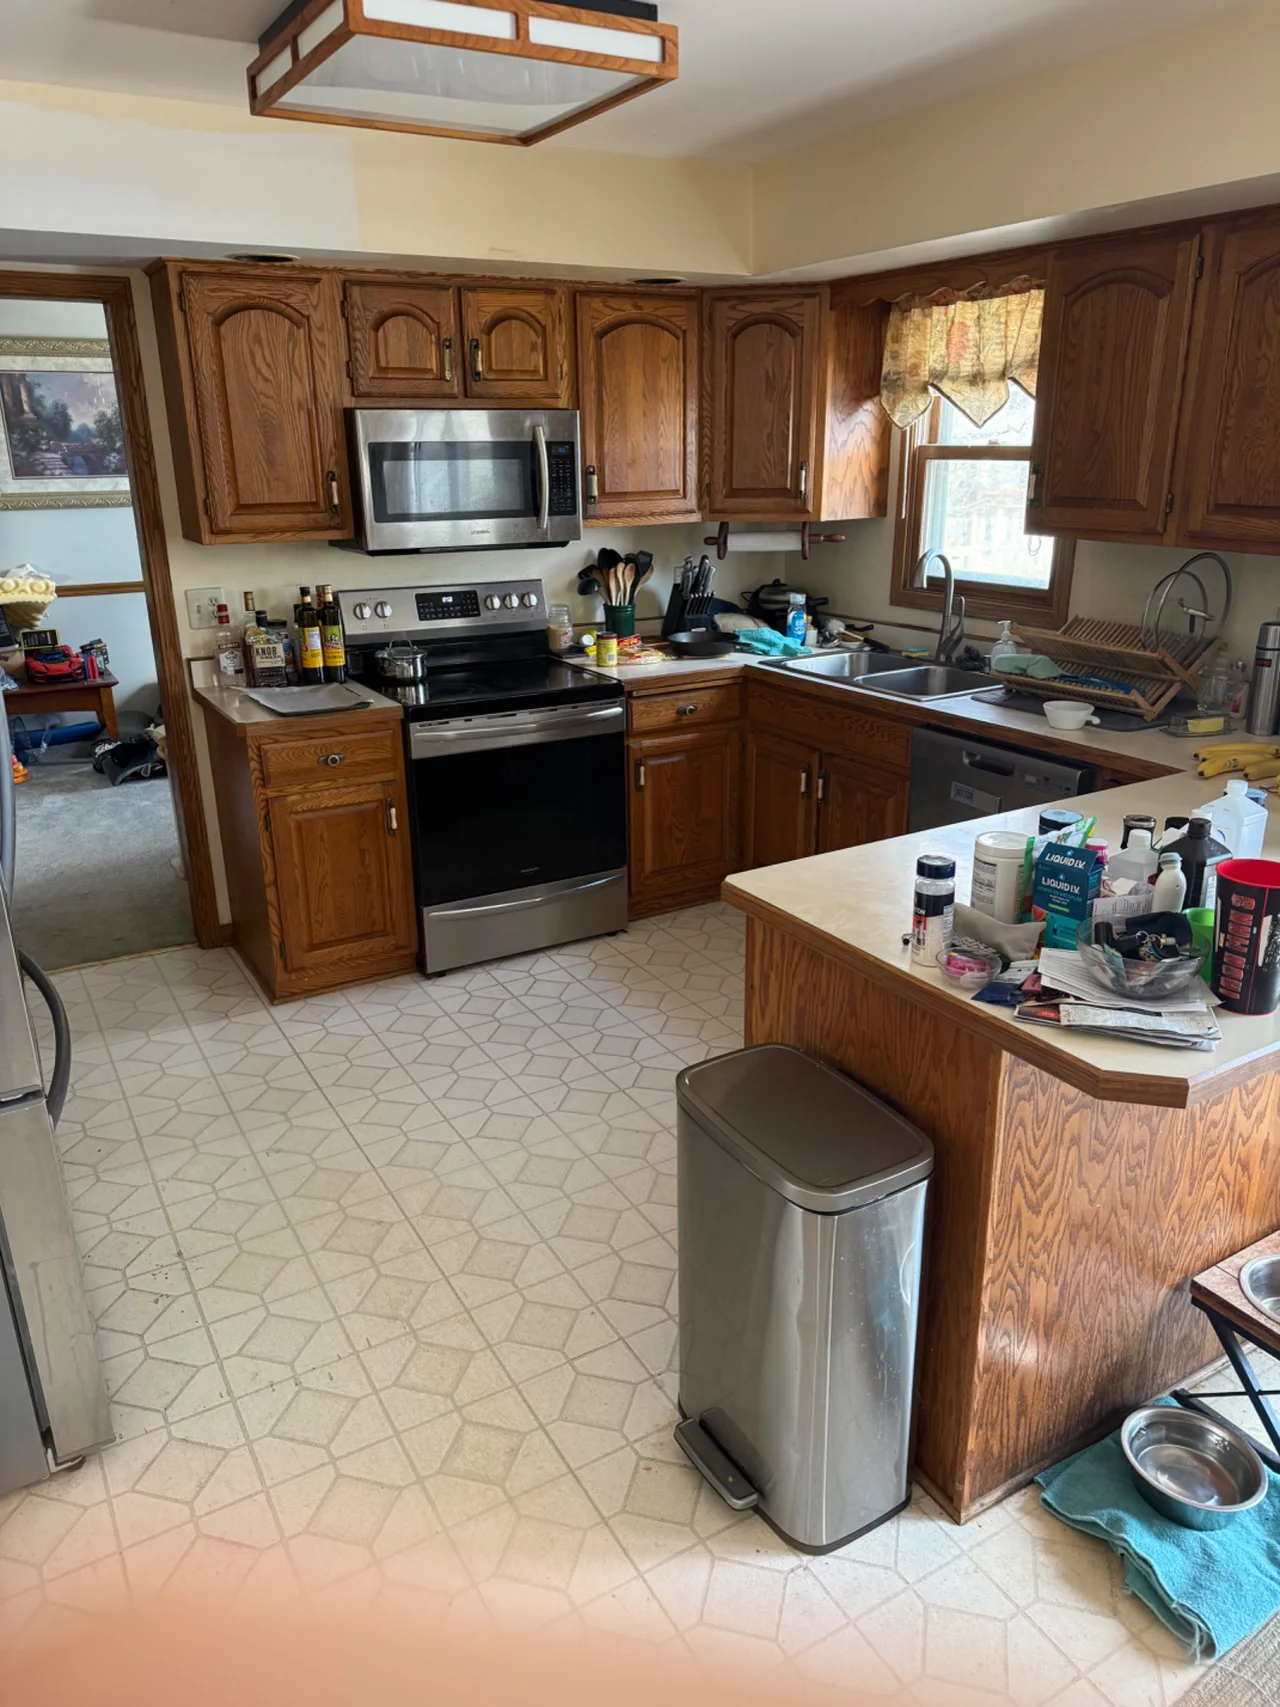
Full kitchen with original oak cabinets and everyday belongings

A direct sale doesn't need a listing, a yard sign, or showings. It isn't secret, though. Everyone on title has to sign, and the lender, the title company, and any lienholder will be part of the closing. Our privacy policy explains how we handle what you send us.

The steps: the address and what you know about the house, one walk-through with no cleaning or repairs first, and a written offer with our name, the price, what stays, who pays which closing costs, and a closing date. Take it to a lawyer; we recommend it. The title company orders the payoff and shows every number on the settlement statement before you sign. If your timeline is the hard part, see how to sell your house fast in Northern Illinois.

No repairs. No cleanup.

  • As-is
  • No showings
  • You pick the closing date.

What sellers say

Swipe to see all 3

  • 1 of 3

    “We had an excellent experience selling our home in McHenry County, IL. [He] was professional, made the selling process easy and was true to his word. I highly recommend this company.”

    Alison M.January 2026Google
  • 2 of 3

    “…No pressure experience, super easy, and he offered me a great deal. I would happily recommend him to anyone looking to sell.”

    Matthew P.November 2025Google
  • 3 of 3

    “…He is very knowledgeable and so easy to work with if you’re looking to sell your home seamlessly and worry free.”

    Jan G.July 2026Google

Google reviews from sellers whose houses our owner bought, posted on the Google listing of his earlier home-buying business. “…” marks a shortened quote; [He] stands in for his name.

Common questions

Common questions about the sale.

  • Can I sell my house if I'm behind on the mortgage?

    Yes. You own the house, and being behind doesn't change who can sell it. In a sale, the title company orders a current payoff and the mortgage is paid from the price at closing, along with any other liens. If the price won't cover them, the lender has to approve a short sale.

  • How many payments can I miss before foreclosure in Illinois?

    There isn't a safe number. Federal servicing rules generally bar a servicer from making the first foreclosure filing until a loan is more than 120 days delinquent, with exceptions, and Illinois requires a court case. Ask your servicer and a housing counselor how that applies to your loan.

  • Is pre-foreclosure the same as foreclosure?

    No. "Pre-foreclosure" is an informal word for being behind with no court case filed. In Illinois, foreclosure begins when the lender files a lawsuit and you're served with a summons. The statute's reinstatement and redemption periods are measured from the service and judgment dates in that case, which our foreclosure page covers.

  • Who should I talk to first?

    A HUD-approved housing counselor or a lawyer, before any buyer. Counselors give independent advice, often at little or no cost, and can explain what your servicer may offer. The Consumer Financial Protection Bureau's counselor search lists agencies by ZIP code. We're a buyer and can't advise you.

  • Can you talk to my lender or get me a loan modification?

    No. We don't contact lenders on an owner's behalf, arrange workouts, or act as anyone's advisor. Those are between you and your servicer, with a counselor or a lawyer helping you. The only thing we do is make a written offer to buy the house, which you can accept or ignore.

  • Will selling protect my credit?

    We can't tell you that and won't guess. Missed payments, a short sale, and a foreclosure may each be reported differently, and a sale doesn't erase payments already missed. Ask a housing counselor or your lender how each option would be reported in your case before you choose one.

  • What if I owe more than the house is worth?

    Then a sale can only close if the lender agrees to accept less than the balance, which is a short sale. The lender decides, on its own schedule, and may ask for financial documents. Start that conversation with a housing counselor or a lawyer, not with a buyer.

  • Will my family or neighbors find out?

    A direct sale has no listing, sign, or showings, but nobody can promise secrecy. Everyone on title has to sign, and the lender, title company, and lienholders are part of the closing. A co-owner or spouse with an interest in the house will need to know before a contract is signed.

  • What if a foreclosure case gets filed while I'm deciding?

    Then the court's dates start to matter. Read the Homeowner Notice that comes with the summons, take the papers to a lawyer or a housing counselor, and see our page on selling a house in foreclosure in Illinois for what the statute says about reinstatement, redemption, and the sale.

Illinois law referenced on this page

  • Consumer Financial Protection Bureau, Regulation X: no first foreclosure filing until a loan is more than 120 days delinquent (12 CFR 1024.41(f))
  • Illinois Mortgage Foreclosure Law, no power of sale; mortgages are foreclosed only in court (735 ILCS 5/15-1405)
  • Illinois Mortgage Foreclosure Law, Homeowner Notice attached to the summons (735 ILCS 5/15-1504.5)
  • Consumer Financial Protection Bureau, find a HUD-approved housing counselor

Related situations

  • ForeclosureA foreclosure case is filed. See what the statute gives you and whether a sale is still possible.
  • Sell as-isStart with the house in its current condition. No repairs or listing preparation before you ask for an offer.
  • Needs major repairsAsk for an offer before deciding what to repair. Share any reports or estimates you already have.
  • Divorce saleOne written offer both spouses can read, no showings, and a closing built around the case.
  • Rental propertyStart with the lease and the property as it stands, whether you live nearby or out of state.

A simple first step

Ready to talk about the house?

In any condition.

Start with the property address and tell us a little about the house. We will explain what happens next.

Prefer to talk?

Call 224-219-0970
Tell us about the house

✓Start with the address. You are not agreeing to sell by sending it.

AS-ISHOUSE BUYERSof Chicagoland

Local cash home buyers serving Elgin and Chicago's northern and western suburbs.

Company

  • About
  • How it works
  • Contact
  • FAQ
  • Guides

Ways we can help

  • Inherited house
  • Foreclosure
  • Sell as-is
  • House with heavy clutter
  • Divorce sale
  • Rental property
  • Needs major repairs
  • Fire or water damage
  • Vacant property
  • Behind on payments
  • Behind on property taxes
  • Code violations
  • Relocating
  • All situations →

Service area

  • All service areas
  • Sell house fast
  • Sell a house as-is

Contact

  • 224-219-0970
  • hello@asischicagoland.com

As-Is House Buyers of Chicagoland

2250 Point Blvd, Suite 335, Elgin, IL 60123

Office hours: Monday–Friday, 9:00 AM–5:00 PM

Serving Elgin and the surrounding Northern Illinois suburbs.

A cash offer may be lower than what a house could sell for on the open market. Compare your options, read the agreement carefully, and talk with your own attorney or a licensed real estate professional before signing if you wish.

© 2026 As-Is House Buyers of Chicagoland. All rights reserved.

  • Privacy
  • Terms
  • TCPA consent
Call